Consultation
 Open an account

SK hynix
28 October 2026
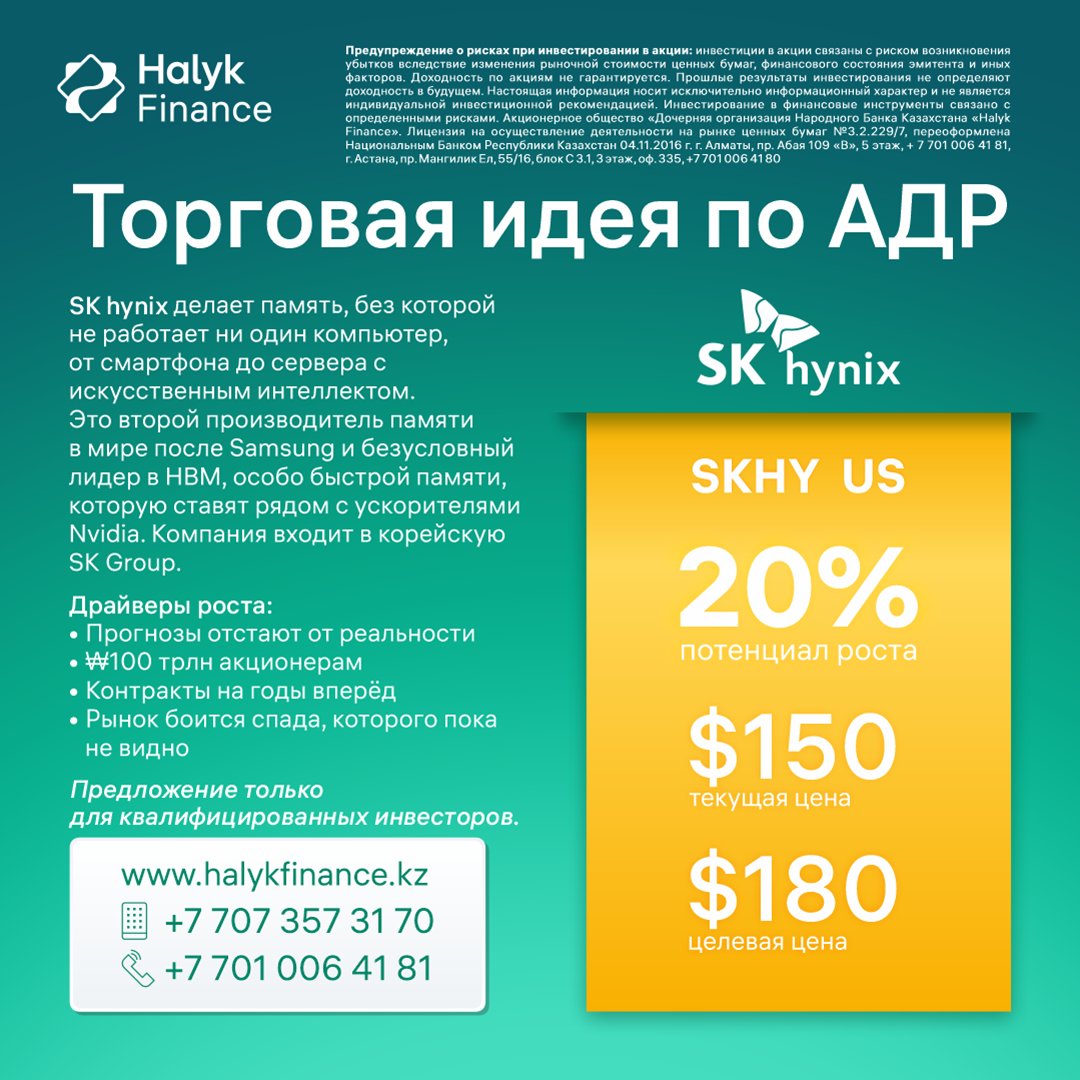
DownloadSK hynix produces the memory essential for every computer, from smartphones to AI servers. It is the world’s second-largest memory manufacturer after Samsung and the undisputed leader in HBM, the ultra-fast memory paired with Nvidia accelerators. The company is part of South Korea’s SK Group. Its shares are traded in Seoul, and from July 2026, they will also be available in the U.S. as ADRs (10 ADRs equal one share). Nearly 70% of sales come from U.S. customers, with the largest contributing about a quarter of revenue in 2025.
Growth drivers:
- Earnings beat expectations. Third-quarter profit was 10% higher than forecasts. The full-year outlook for 2026 is ₩262.7 trillion in operating profit. In the first nine months, the company already earned ₩181.5 trillion; analysts project about ₩81 trillion for the fourth quarter, which is lower than in the previous period. However, the company expects DRAM sales to grow by about a quarter, and DRAM prices continue to rise. We believe 2026 and 2027 forecasts will be revised upward. For 2027, the consensus is currently ₩404 trillion, while some Korean brokers are already estimating ₩450 trillion or more. The market, however, values the company at just about three times its annual earnings.
- ₩100 trillion returned to shareholders. In 2026, the company will return about ₩100 trillion to shareholders. Part of this has already been done: ₩40 trillion was used for a share buyback that concluded last week. Another ₩60 trillion is still ahead, equating to 5–6% of market capitalization. Annual dividends will be at least ₩30 trillion, translating to a yield of about 2.8%, compared to 0.2% a year earlier. ₩14 trillion of this (₩20,000 per share) has already been declared for the third quarter. The board has approved a new ₩20 trillion buyback, and future programs will be approved quarterly. The CFO noted that the shares are undervalued. The company has the funds: free cash flow for the first half of the year alone reached ₩73 trillion, and the company plans to return at least half of it to shareholders.
- Multi-year contracts secured. Previously, memory was sold almost like a commodity, at spot prices. Now, 14 major customers, including cloud giants, have signed average five-year contracts. They will account for over half of SK hynix’s capacity in 2027–2028, with prices locked within a pre-agreed range. This makes profits more predictable, and the next downturn, when it comes, will be milder. HBM prices and volumes for 2027 have already been agreed upon, factoring in the more expensive HBM4, and the company expects significant revenue and profit growth from this product.
- The market fears a downturn that isn’t materializing. Even after the October 28 surge, the stock remains nearly half as cheap as its June peak. Meanwhile, quarterly operating profit has grown from ₩60.5 trillion to ₩83.3 trillion over this period. SK hynix is currently trading at about 3.1 times its annual earnings, cheaper than Micron (4.5x) and Samsung (3.4x). Cash on hand covers about 9% of its market capitalization. Foreign investors, who were actively selling Korean stocks in October, resumed buying on October 28, and if this trend continues, the revaluation could accelerate.
This offer is available exclusively to qualified investors.