Consultation
 Open an account

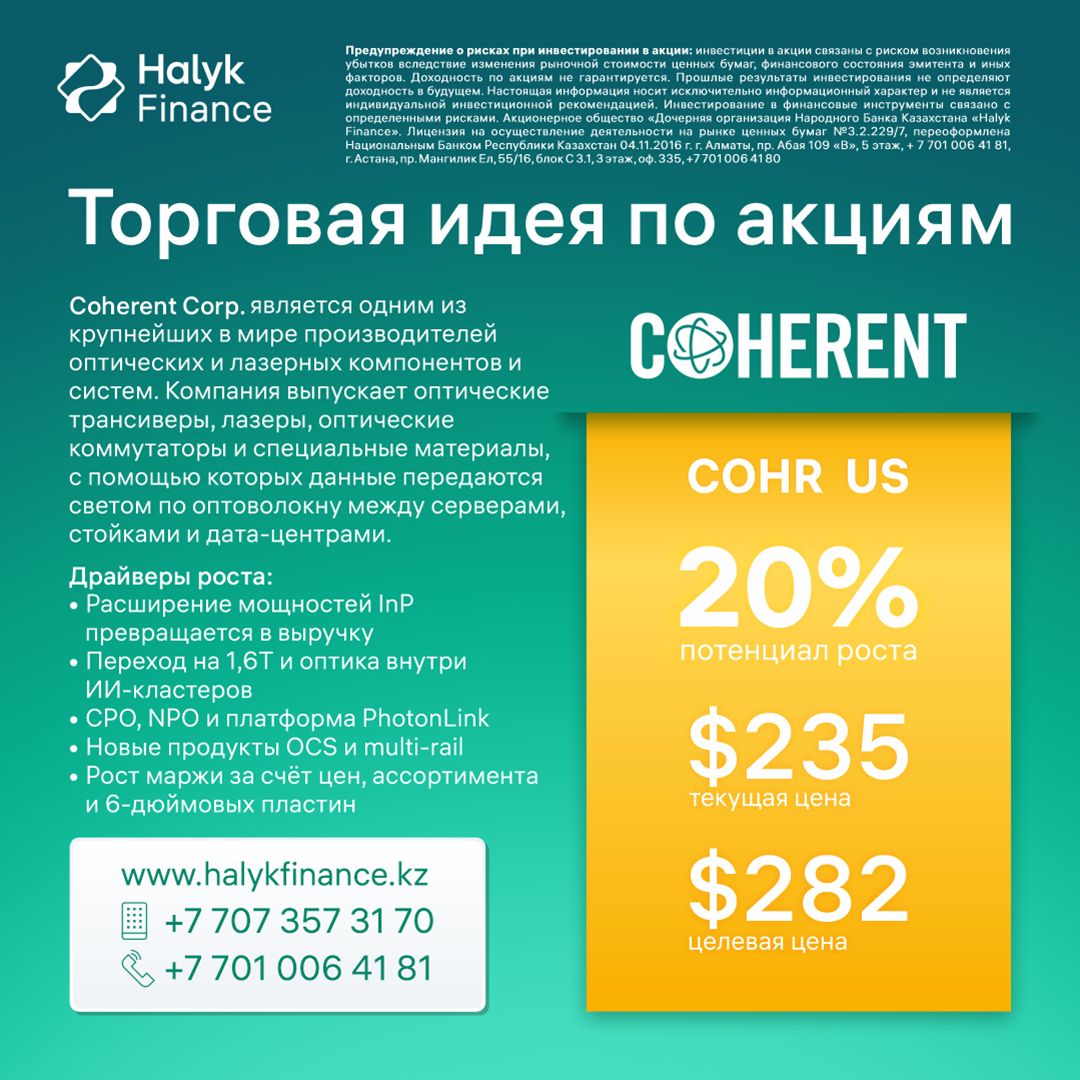
Halyk Finance Trading Idea: Coherent Corp.
28 October 2026
DownloadCoherent Corp. is one of the world’s largest manufacturers of optical and laser components and systems. The company produces optical transceivers, lasers, optical switches, and specialty materials that enable data transmission via light through fiber optics between servers, racks, and data centers. In simple terms, Coherent manufactures “light cables” for AI. The more AI accelerators hyperscalers cluster together, the more optical connections they require.
Growth drivers:
- Expansion of InP capacity translates into revenue. The main constraint on Coherent’s growth in recent quarters has not been demand but a shortage of its own indium phosphide (InP) lasers. Management planned to double internal production by the end of Q1 FY27 (quarter ended 09/30/2026), a quarter ahead of the original schedule, and more than double it again by the end of calendar year 2027. InP laser output already grew 80% year-over-year in Q4 FY26, and data center revenue is expected to increase by more than 80% year-over-year in Q1 FY27, according to J.P. Morgan. All expansion capacity is already sold: FY27 is effectively contracted, orders are booked through 2028, and long-term agreements (LTAs) extend through the end of the decade. At the same time, in-house lasers are replacing more expensive purchases from third-party suppliers, so capacity growth simultaneously boosts both sales and margins. The consensus expects FY27 revenue growth of ~51% to $10.8 billion and EPS growth of ~77%.
- Transition to 1.6T and optics within AI clusters. Each new generation of AI accelerators requires faster connections, and the market is shifting from 800G transceivers to 1.6T. According to LightCounting, the 1.6T segment is expected to grow at a CAGR of around 120% and reach ~$40 billion by 2030. Coherent is already ramping up 1.6T shipments and remains one of the few manufacturers with a full suite of in-house components. A second independent driver is the shift of scale-up networks—those connecting accelerators within a rack—from copper to optics. According to management estimates, such networks have roughly 10 times more connections than scale-out networks, so this transition creates an additional market beyond data center capital expenditure growth. The company’s total addressable market is estimated at $90 billion by the end of the decade.
- CPO, NPO, and the PhotonLink platform. In September 2026, Coherent introduced PhotonLink, an integrated optical platform for CPO, NPO, and chip-to-chip optical interconnect architectures. In such solutions, optics are moved closer to the processor, reducing power consumption and increasing bandwidth. NVIDIA serves as the anchor customer for CPO, another major customer has been selected as the anchor for NPO, and the total number of projects exceeds 25. CPO revenue for scale-out networks will begin in the quarter ending December 2026, with scale-up and NPO scaling expected in the second half of 2027. According to management estimates, Coherent’s content per chip could reach ~$15,000 for a 100T bandwidth chip, and the PhotonLink addressable market is projected at $30 billion by 2030. The platform’s gross margin is above the company average.
- New OCS and multi-rail products. Coherent’s optical switching solutions (OCS) route optical signals without converting them to electrical, saving energy and simplifying the architecture of large AI clusters. The company has doubled its addressable market estimate for OCS to more than $4 billion, and segment revenue is growing quarter-over-quarter based on the 320×320 platform. Multi-rail solutions for optical links, with an addressable market exceeding $2 billion by 2030, will begin generating revenue in the first half of 2027. Here, Coherent leverages the pump laser shortage—where it is one of only two significant global suppliers—to sell not individual components but complete systems with higher margins. Both products are layered on top of the growing transceiver business and enhance the portfolio. For investors, this is important as it reduces the company’s dependence on a single product and a single generation of transceivers.
- Margin growth driven by pricing, portfolio expansion, and 6-inch wafers. Coherent’s gross margin (non-GAAP) increased from 34% in FY24 to 40.2% in Q4 FY26 (40.2% GAAP: 38.5%) and has risen in 8 of the last 9 quarters. Management is targeting a level above 42% and expects further growth. There are three sources of this improvement. First, capacity constraints allow price increases on existing products. Second, new products (PhotonLink, OCS, multi-rail) carry above-average margins. Third, the transition to 6-inch InP wafers yields more than four times as many die per wafer at less than half the cost per die compared to 3-inch wafers. According to Halyk Research, every +100 bps of gross margin adds about $0.50 to the FY28 EPS forecast. Additional support is expected from the recovery of the industrial segment. Margin growth drives profit growth ahead of revenue, and management explicitly factors this into its FY27 outlook.